 (+91) 842-700-1426
 agriparts@jcblmail.com
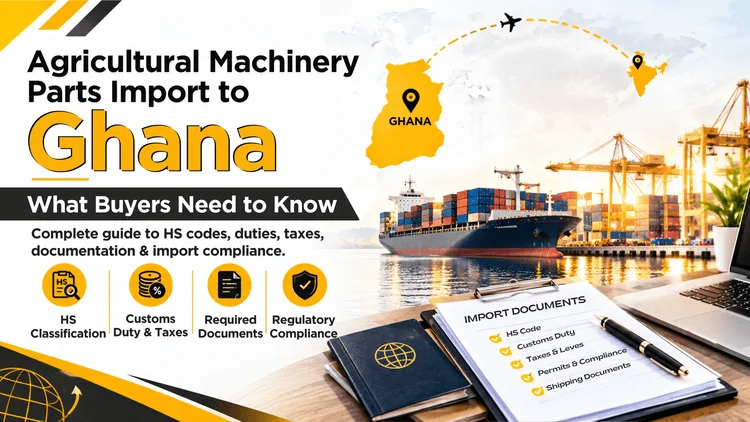
Importing agricultural machinery parts into Ghana requires accurate HS classification, customs valuation, duty and tax assessment, documentation, and regulatory compliance. The applicable import duty is not the same for every agricultural machinery part. It depends on the specific tariff classification and applicable customs treatment.
Ghana uses the ECOWAS Common External Tariff (CET) and processes import declarations through the Integrated Customs Management System (ICUMS). Importers should confirm the applicable tariff line and product-specific requirements before shipping.
What Are the Requirements for Importing Agricultural Machinery Parts into Ghana?
Importers generally need to identify the correct HS code, determine the applicable customs duty and taxes, prepare the required commercial and shipping documents, obtain any product-specific permits, and submit the import declaration through ICUMS. Customs then processes classification, valuation and approval before the importer pays the assessed duties and taxes and completes any required examination and release procedures.
What Import Duty Applies to Agricultural Machinery Parts in Ghana?
Ghana applies the ECOWAS Common External Tariff, which has five main customs-duty bands:
| CET band | Duty rate | General category |
| Band 0 | 0% | Essential social goods |
| Band 1 | 5% | Basic necessities, raw materials, capital goods and specific inputs |
| Band 2 | 10% | Intermediate goods and inputs |
| Band 3 | 20% | Finished goods |
| Band 4 | 35% | Specific goods for economic development |
These bands should not be interpreted as a single rate for all agricultural machinery parts. The exact rate depends on the part’s HS classification and the applicable tariff line.
Why Does HS Classification Matter?
The HS code identifies the product for customs purposes and affects its tariff treatment. Ghana’s Customs Technical Services Bureau (CTSB) handles classification, valuation, and determination of origin for customs assessment.
For a machinery part, the importer should have an accurate description covering relevant characteristics such as:
- Part name and function
- Machinery or equipment for which it is designed
- Manufacturer and part number
- Material or composition where relevant
- Country of origin
A tractor and a replacement component for that tractor should not automatically be treated as having the same HS classification. Therefore, an importer should verify the tariff line for the specific part, rather than applying the rate of the complete machine.
What Taxes Apply to Imported Machinery Parts?
Customs duty is only one part of the import tax calculation.
Under Ghana’s Value Added Tax Act, 2025, effective from 1 January 2026, the current rates are:
- VAT: 15%
- National Health Insurance Levy (NHIL): 2.5%
- Ghana Education Trust Fund Levy (GETFund): 2.5%
Together, these amount to an effective 20% on the applicable VAT value. GRA confirms that these rates apply to imports unless the goods are specifically exempt.
Other customs charges or levies may also apply depending on the relevant tariff treatment. GRA’s customs information identifies charges such as the ECOWAS levy, African Union levy, processing fee, examination fee, and other applicable import levies.
How Is Import Duty Calculated?
For general imports, the applicable customs duty is determined using the customs value and the tariff rate for the product.
A simplified calculation is:
Customs duty = Applicable customs value × applicable duty rate
For example, if the customs value used for assessment was US$50,000 and the applicable duty rate was 5%:
US$50,000 × 5% = US$2,500 customs duty
This is only an illustration of customs duty. It does not represent the total amount payable on a shipment.
Importers should use the customs assessment generated through ICUMS because the final liability can include applicable VAT, NHIL, GETFund, and other customs charges.
What Documents Are Required to Import Agricultural Machinery Parts into Ghana?
GRA identifies key documents required for import clearance, including:
- Original Bill of Lading or Waybill
- Attested commercial invoice
- Packing list
- Import Declaration Form (IDF)
- GRA TIN or GhanaCard PIN
- Required permits from relevant regulatory agencies, where applicable
Product descriptions, quantities, values, and part information should be consistent across the commercial invoice, packing list, shipping documents, and customs declaration.
Do Agricultural Machinery Parts Need an Import Permit or Certification?
Not every agricultural machinery part automatically requires the same permit or certification.
GRA states that permits may be required from relevant regulatory agencies depending on the goods. These can include requirements involving agencies such as the Ghana Standards Authority (GSA).
The requirement should therefore be checked against the specific product and applicable Ghanaian standards or regulatory controls before shipment. An importer should not assume that every agricultural machinery spare part requires GSA certification simply because it is used in agricultural equipment.
How Does Customs Clearance Work in Ghana?
Ghana processes import declarations electronically through ICUMS. The general customs process is:
- Determine the correct HS classification.
- Prepare the required import and shipping documents.
- Submit the declaration through ICUMS, normally through a clearing agent.
- Customs processes classification, valuation, and approval.
- Pay the assessed duties and taxes.
- Complete examination or scanning where required.
- Obtain customs release and move the goods through the exit process.
GRA states that ICUMS processes declarations through classification, valuation, and approval. Shipments may then be assigned different examination or release channels based on customs risk procedures.
Can Agricultural Machinery Parts Qualify for Duty Exemptions?
A machinery part is not automatically exempt from customs duty simply because it is used in agriculture.
GRA states that exemptions apply to categories established by law, including certain privileged persons and institutions, and require appropriate approval where applicable.
Therefore, an importer should verify whether a specific exemption legally applies to the product, importer, and import regime before relying on duty-free treatment.
What Should Importers Check Before Shipping?
Before dispatching agricultural machinery parts to Ghana, businesses should verify:
- HS classification: Confirm the tariff line for the exact part.
- Duty rate: Check the current ECOWAS/Ghana tariff treatment.
- Tax liability: Account for VAT, NHIL, GETFund, and applicable customs charges.
- Customs value: Ensure the information used for customs valuation is accurate.
- Documents: Prepare the invoice, packing list, bill of lading/waybill, IDF, and identification details.
- Regulatory controls: Check whether the particular part requires a permit, inspection, or conformity assessment.
- ICUMS declaration: Ensure the customs declaration accurately reflects the shipment.
- Product descriptions: Keep descriptions and quantities consistent across all documents.
Conclusion
Importing agricultural machinery parts into Ghana requires accurate HS classification, customs valuation, tax assessment, documentation, and regulatory checks. The ECOWAS CET determines the applicable customs-duty framework, while Ghana’s current VAT system applies 15% VAT plus 2.5% NHIL and 2.5% GETFund to taxable imports.
For B2B shipments, the most important step is to verify the exact tariff classification and product-specific requirements before dispatch. This helps the importer calculate the expected landed cost and prepare the correct documentation for ICUMS customs clearance.
FAQs
There is no single duty rate for all agricultural machinery parts. Ghana’s ECOWAS CET has duty bands of 0%, 5%, 10%, 20%, and 35%, with the applicable rate determined by the specific tariff classification.
There is no universal HS code for every agricultural machinery part. Classification depends on the specific product, its function, characteristics and the applicable tariff schedule. Ghana Customs’ classification process should be used to determine the appropriate tariff line.
Taxable imports are generally subject to 15% VAT, 2.5% NHIL and 2.5% GETFund under the VAT framework effective from 1 January 2026, unless a specific exemption applies.
Key documents include the Bill of Lading or waybill, attested invoice, packing list, Import Declaration Form, TIN or GhanaCard PIN, and any applicable regulatory permits.
Not necessarily. Requirements depend on the specific product and applicable standards or regulatory controls. Importers should verify the requirements for the exact part before shipment.
ICUMS processes customs declarations through classification, valuation, and approval, after which applicable duties and taxes are paid and the shipment proceeds through the relevant examination or release process.